

“Complex systems are tightly coupled. That is why failures cascade.” – Charles Perrow
Much of the analysis of the current Middle East conflict is focused on the oil price. Within the past 24 hours the price has surged above $120 before falling back to around $92.
The oil price is the first-order effect of having the Strait of Hormuz, and the infrastructure upstream of this narrow body of water, disrupted.
That is understandable. Roughly 40 percent of globally traded seaborne oil passes through that narrow waterway. Any serious disruption would immediately push up oil prices and squeeze economies already struggling with inflation and slowing growth.
However, the second and third order effects will clearly demonstrate just how interconnected, and how fragile, the modern global economy has become.
Production is ultimately the combination of energy and matter. Oil and LNG are flows of energy. This conflict is also disrupting flows of matter.
What moves through the Strait of Hormuz cannot be captured by a discussion of oil alone. The industrial metabolism of a large part of the global economy flows through this part of the world.
Modern civilisation does not simply run on energy. It runs on flows — flows of energy, materials and chemical feedstocks that underpin everything from agriculture to semiconductors. When those flows are interrupted the effects propagate through the system in strange, cascading, and often unexpected ways.
The kinetic war now unfolding in the Middle East may ultimately cause second and third order disruptions that rival, or even exceed, the direct impact of higher oil prices.
Because the Strait of Hormuz is not just an oil chokepoint.
It is one of the most important industrial supply arteries on Earth.
Fertiliser: the foundation of food production
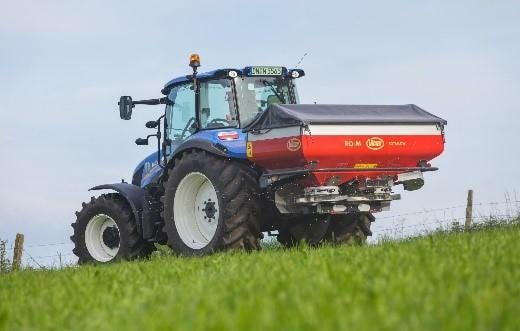
One of the least appreciated flows through the Gulf is fertiliser.
The Middle East is a major exporter of nitrogen fertilisers such as ammonia and urea, produced using natural gas as the primary feedstock.
Urea is the most widely used nitrogen fertiliser in the world, underpinning a significant share of global food production. New Zealand is directly exposed to this supply chain.
Each year New Zealand imports around 354,000 tonnes of urea, approximately 75 percent of which comes from Saudi Arabia and other Gulf producers whose exports transit through the Strait of Hormuz. That fertiliser is spread across dairy and cropping land across the country.
If those shipments slow or stop, the consequences will not be immediate. Fertiliser is often held in storage or already moving through the shipping system.
But several months later the effects begin to appear.
Reduced fertiliser application leads to slower pasture growth, reduced crop yields and lower livestock productivity.
A disruption thousands of kilometres away in the Persian Gulf can ripple through New Zealand’s agricultural output.
Sulphur: the invisible industrial input
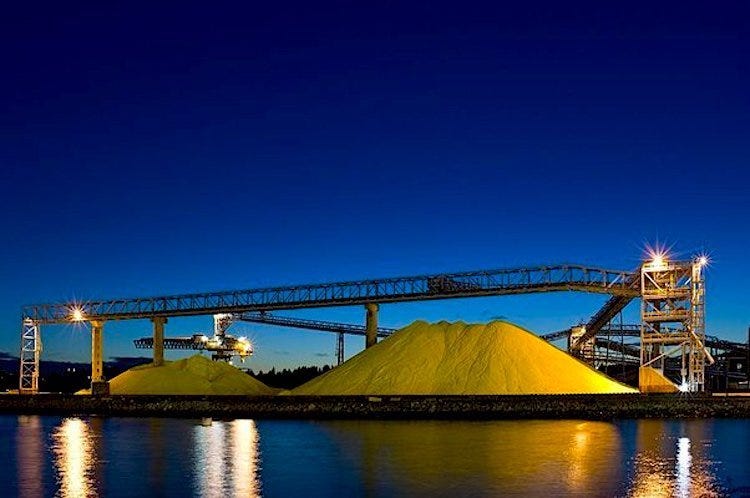
Another largely invisible flow is sulphur.
Sulphur is a by-product of oil and gas refining and large volumes are exported from Gulf producers. It is used to manufacture sulphuric acid, one of the most important industrial chemicals in the world.
Sulphuric acid underpins industrial processes such as phosphate fertiliser production, copper and nickel mining, chemical manufacturing and battery production.
If sulphur supply tightens, the effects cascade across multiple industries simultaneously.
Mining operations become more expensive. Fertiliser production slows. Chemical plants struggle to maintain output.
Very few people think about sulphur — until industry can no longer obtain it.
LNG: electricity systems running on ships
Liquefied natural gas is another critical flow moving through the Gulf.
Countries such as Japan, South Korea and Taiwan — and perhaps New Zealand in the not too distant future — rely heavily on LNG imports for electricity generation.
Taiwan is particularly vulnerable. Its electricity system is highly dependent on imported LNG and maintains only limited storage, often only around a week to ten days of supply.
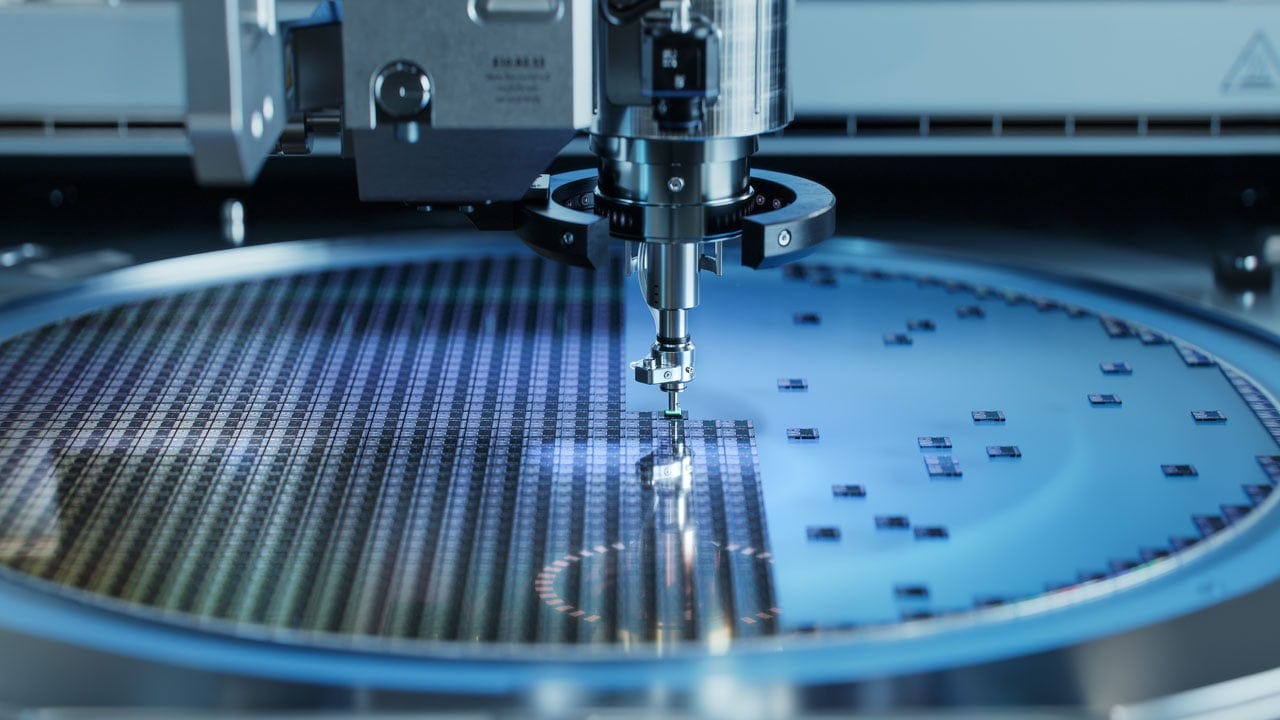
If LNG cargoes stop arriving in Taiwan — home to the world’s most important semiconductor manufacturing industry — the consequences escalate quickly.
Gas-fired power plants begin to shut down. Electricity rationing starts. Industrial production slows. Semiconductor fabrication becomes unreliable and thousands of downstream products are affected.
The average electric vehicle, for example, uses around 150 different types of chips, many of which are manufactured by TSMC (Taiwan Semiconductor Manufacturing Company).
This is where the interconnected nature of the modern economy becomes obvious.
Shipping disruptions and infrastructure destruction in the Persian Gulf can eventually ripple into global semiconductor supply chains.
Petrochemicals: the raw materials of modern life
The Gulf is also a major exporter of petrochemical feedstocks.
These include methanol, ethylene, polyethylene and polypropylene.
These chemicals are the precursors used to manufacture plastics, packaging, synthetic fabrics, car parts and electronics.
When petrochemical supply tightens the effects ripple through global manufacturing. Factories thousands of kilometres away suddenly discover that critical inputs have become scarce or far more expensive.
Not all oil is created equal
Even the oil market itself is more complicated than most people realise.
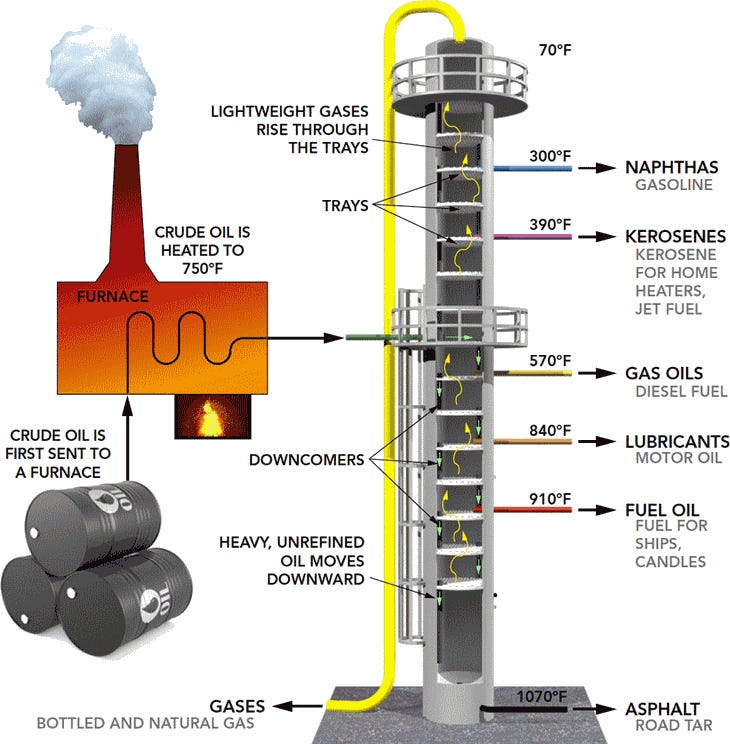
Crude oil is not a single uniform commodity. It is a complex mixture of hydrocarbons.
Modern refineries are designed to process specific blends of crude oils in order to produce the fuels the economy actually needs.
Many refineries in Asia were specifically configured to process medium sour crudes from the Middle East. If those crude streams are disrupted, refineries must substitute other grades, often lighter crudes from the United States, West Africa or the North Sea.
Lighter crude produces more naphtha and petrol, but less diesel and jet fuel.
That creates a counterintuitive outcome.
The world could find itself short of diesel while drowning in surplus naphtha.
Diesel, as I have said many times before, powers the industrial economy. It powers trucking, shipping, fishing, forestry, agriculture and construction.
Naphtha, by contrast, feeds petrochemical plants that have limited capacity to absorb additional supply.
The refining system is therefore forced into a rapid and complex re-optimisation.
A global scramble inside refineries
The Strait of Hormuz does not just carry twenty percent of global oil supply. It carries something closer to forty percent of the oil that actually moves through international markets.
Most oil produced in the world is consumed in the country where it is produced. It is the traded barrels that set the global price — and almost half of those pass through this single narrow shipping lane.
Across Asia and the US Gulf Coast, refinery operators are racing to rebalance the feedstock composition of their refineries.
They are adjusting crude purchases, changing refinery operating conditions and responding in real time to rapidly shifting product prices.
We could see a situation where diesel prices surge while gasoline or naphtha prices fall due to the mixture of feedstocks available as Middle Eastern supplies are disrupted.
Jet fuel is a middle distillate similar to diesel, and we have already seen rapid price spikes as the availability of this fraction tightens and the global aviation industry grapples with potential shortages.
The global scramble for fuel begins
Evidence of this reconfiguration is already emerging.
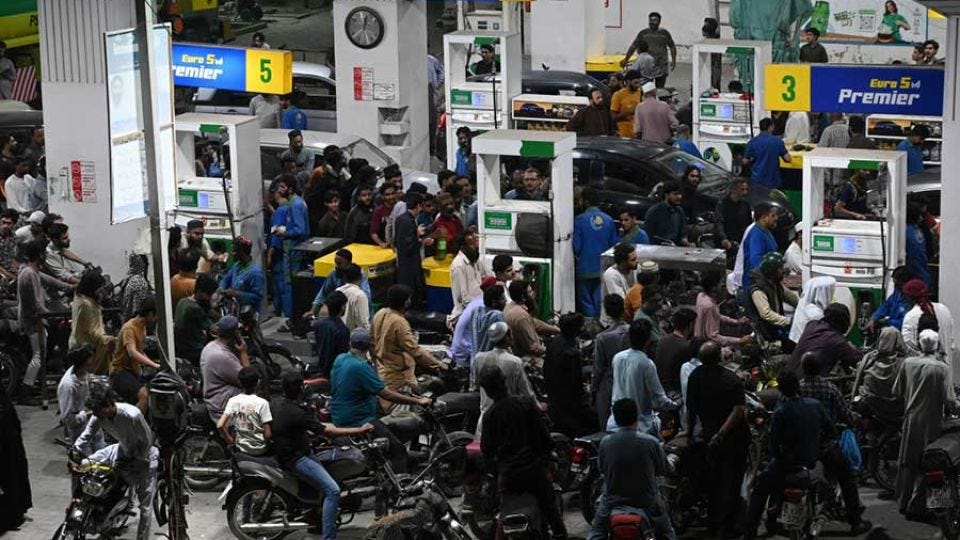
Recent reports indicate that shipments of diesel and jet fuel originally destined for Africa have reversed course and headed toward Asia, where prices and demand are surging.
Across the world fuel markets are tightening and governments are scrambling to secure supply.
This is the global fuel trading system reconfiguring itself in real time.
The process is chaotic and often produces shortages and price spikes while the system searches for a new equilibrium.
What this means for New Zealand
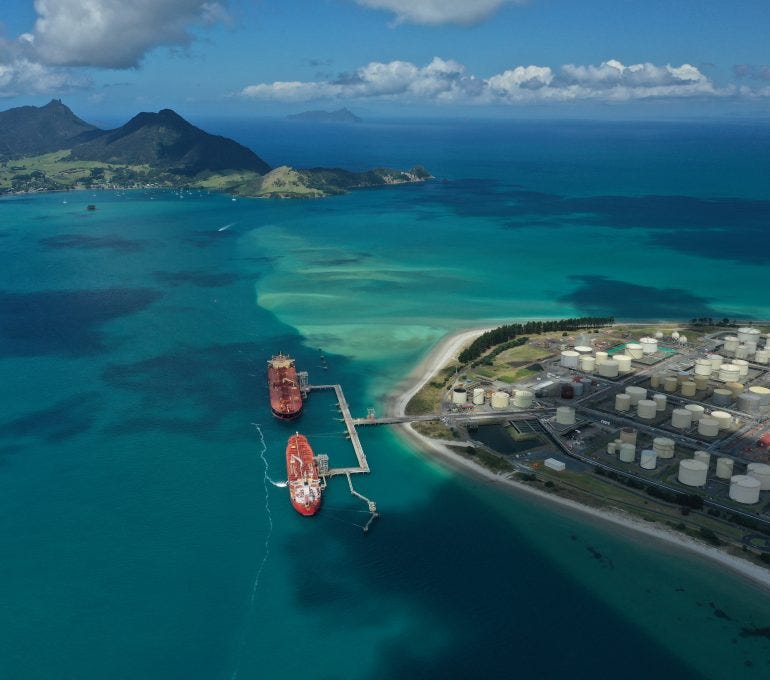
New Zealand sits at the very end of the global fuel supply chain.
We are an island nation with limited strategic importance and a very high dependence on imported energy and industrial inputs.
Since the closure of the Marsden Point refinery, all petrol, diesel and jet fuel are imported from overseas refineries, primarily in Southeast Asia.
In normal times this system works well. But when global supply tightens, cracks begin to appear that expose significant vulnerability.
In a tight global market the marginal cargo does not always go to the most distant customer. It goes to the highest bidder.
New Zealand does have long-term supply contracts and minimum stockholding requirements that provide some buffer.
But ultimately the country still relies on international product markets and long shipping routes.
In a global fuel shortage, the self-interest of other countries, our lack of self-sufficiency and our distance from major refining centres could become decisive factors.
This is not the 1970s oil shock
Many commentators instinctively compare the current situation to the oil shocks of the 1970s.
But the world economy of the 1970s was far simpler and far less interconnected.
Supply chains were shorter. Industrial production was more geographically concentrated. Companies held larger inventories of materials and components.
Just-in-time manufacturing had not yet become the dominant model.
Today production is fragmented across continents in pursuit of efficiency. A single manufactured product may contain components sourced from half a dozen countries and several highly specialised suppliers.
The result is extraordinary efficiency.
But it also creates unprecedented systemic fragility.
Modern supply chains often depend on extremely specialised materials produced in only one or two facilities globally.
After the 2011 earthquake and tsunami in Japan, a small factory producing a specialised pigment used in automotive paint shut down. That pigment was used across the global automotive industry.
Within weeks major manufacturers including Ford were forced to slow or halt production.
It was not steel, aluminium or engines that stopped the factories.
It was paint pigment.
This is the defining feature of modern industrial systems, small disruptions can propagate into large consequences.
The biophysical reality: modern economies run on flows
This is not just about oil.
It is about flows.
Modern industrial civilisation operates on continuous throughput. Energy, materials and components move around the planet in tightly synchronised networks.
Globalisation optimised this system for efficiency.
It optimised for minimal inventories, just-in-time logistics, long supply chains and highly specialised production.
The system works extraordinarily well — until something breaks.
When a critical node fails the effects propagate through the network in ways that are impossible to accurately predict.
Food prices rise. Manufacturing slows. Electricity systems struggle. Supply chains seize up. Budget forecasts deteriorate. Political instability and upheaval follow.
The world discovers, very quickly, how dependent everything is on everything else.
The reality of the modern era
Industrial civilisation is not a collection of independent sectors.
It is a single tightly coupled system.
Break any of the key arterial flows and the shock travels through the entire system.
For three decades the global economy has optimised relentlessly for efficiency.
But efficiency removes redundancy, and redundancy is what makes systems resilient.
The modern global economy behaves less like a collection of independent industries and more like a single interconnected machine.
The world may now discover that efficiency and resilience are often opposites.
The conflict in the Middle East has now been underway for ten days.
If the Strait of Hormuz remains disrupted, the world may soon rediscover just how interconnected — and how fragile — the modern global economy really is.
Thanks as always, please like and share far and wide if you find these pieces interesting.
Larry
Great analysis as usual. Would be good to add that coal supply is also impacted. As countries pull in their backup plans without oil, coal pricing has gone up from $110 to $150 and rising. While we have a fair amount on the Huntly stockpile we will need to be prepared to pay more to secure new coal if we can.
Thanks very much for this Larry! I'm calling on everyone who reads about South Korea's potential actions to restrict oil exports to email oilsecurity@mbie.govt.nz in support of the email I sent them yesterday calling for an immediate start to rationing: https://www.linkedin.com/posts/nathansurendran_advocacy-group-calls-for-national-fuel-security-activity-7437063277991407616-ZnHD?utm_source=share&utm_medium=member_android&rcm=ACoAAAEkA5wBziBF9DtlVp-191Cv5w-E5coil2Q